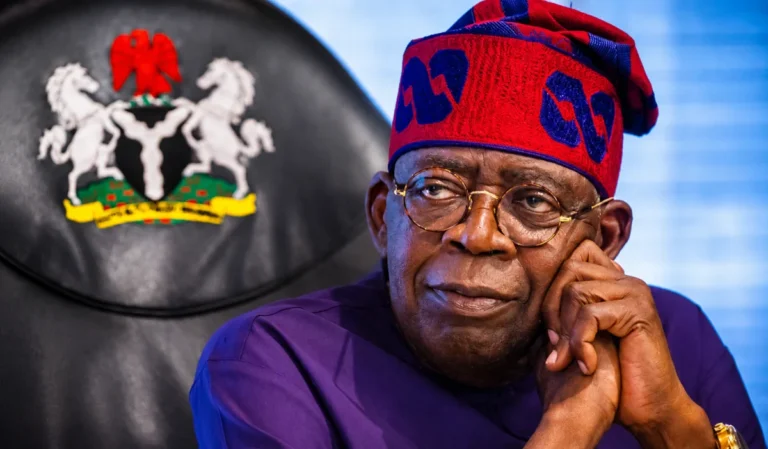
President Bola Ahmed Tinubu has underscored the profound transformation of Nigeria’s financial ecosystem, asserting that working-class citizens and tertiary institution students can now seamlessly access essential loans through robust financing schemes initiated or significantly strengthened by his administration. In an extensive statement released via his official social media handle on Monday, the President detailed the tangible milestones achieved through various federal credit and loan initiatives designed to transition the nation toward a modern, credit-based economy. This comprehensive financial overhaul represents a strategic pivot from economic stabilization policies to proactive wealth creation and empowerment, fundamentally altering how everyday Nigerians interact with financial institutions.
The aggressive structural push toward financial inclusivity comes at a critical juncture for the West African economic giant. For decades, the absence of a reliable credit reporting system and the stringent collateral demands of traditional commercial banks effectively locked the vast majority of working-class citizens and small business owners out of the formal financial sector. By deploying targeted institutional frameworks, the current administration aims to bridge this historical deficit, providing the financial leverage necessary for individuals to meet urgent familial needs and for enterprises to scale operations, spur innovation, and generate employment.
Institutional Frameworks Driving the Credit Revolution
At the core of the federal government’s financial inclusion strategy are specialized institutions tailored to address specific sectors of the economy. President Tinubu specifically highlighted the Nigerian Consumer Credit Corporation (CREDICORP) as the primary vehicle through which working Nigerians can access consumer credit to purchase essential goods and pay over time. Concurrently, the Nigerian Education Loan Fund (NELFUND) has been empowered to finance higher education for students, a move that education sector stakeholders note has already begun to curb alarming tertiary dropout rates nationwide.
Beyond consumer and educational credit, the administration continues to channel robust financial support to the enterprise sector via traditional pillars such as the Bank of Industry (BOI) and the Development Bank of Nigeria (DBN). However, the critical missing link in SME financing—risk aversion by commercial lenders—has been aggressively tackled by the National Credit Guarantee Company (NCGC). Operating as a risk-sharing mechanism, the NCGC partners with mainstream financial institutions to absorb a significant portion of lending risks, thereby instilling the confidence required to extend credit to viable businesses that lack traditional collateral or established credit histories.
A Year of Milestone Achievements for the National Credit Guarantee Company
The National Credit Guarantee Company, a cornerstone of the administration’s enterprise financing strategy, has marked its first full year of active operations with remarkable performance metrics. According to data provided by the presidency, the NCGC currently collaborates with 19 financial institutions, comprising 13 commercial banks, three microfinance banks, and three development finance institutions.
Within its inaugural year, the NCGC has successfully issued ₦21.59 billion in guarantees. Leveraging these federal-backed guarantees, participating financial institutions have extended an impressive ₦46.95 billion in loans to small and medium-sized enterprises across the country. This translates to an impressive multiplier effect, where every single naira in guarantees has helped unlock approximately ₦2.17 in commercial credit.
Geographical spread and demographic inclusivity have been central to the deployment of these funds. Official records indicate that 67,512 borrowers spread across 25 states and the Federal Capital Territory (FCT) have received credit backed by the NCGC. Notably, the initiative has prioritized gender inclusivity, with 11,374 women securing financial backing to sustain and expand their commercial enterprises. Furthermore, the data reveals a profound structural shift: 33.5 percent of the total beneficiaries represent first-time formal borrowers. This milestone successfully integrates more than 22,000 Nigerians into the formal credit system for the very first time, providing them with verifiable credit histories that will facilitate easier borrowing in the future.
Socio-Economic Implications and Employment Generation
The broader macroeconomic implications of expanding credit access extend far beyond individual balance sheets, serving as a primary driver for job creation and poverty reduction. Economic analysts note that when traders and small-scale manufacturers gain access to working capital, they are better positioned to optimize inventory, invest in modern equipment, and respond robustly to market demand cycles.
The NCGC estimates that the businesses supported through its guarantee framework currently account for an estimated 661,291 direct and indirect jobs across Nigeria. From local retail traders stocking up ahead of peak commercial seasons to light manufacturers acquiring additional machinery to fulfill larger corporate orders, the ripple effects of accessible credit are permeating various layers of the domestic economy. This liquidity injection acts as a vital cushion against inflationary pressures, empowering consumers to smooth out their consumption patterns while allowing entrepreneurs to plan capital expenditures with greater certainty.
Chronology of the Administration’s Financial Reforms
The journey toward a credit-based Nigerian economy did not happen overnight; it represents the methodical implementation of campaign promises and policy declarations made since the inception of the Tinubu administration in May 2023.
Upon assuming office, President Tinubu initiated sweeping macroeconomic reforms, notably the removal of the petrol subsidy and the unification of foreign exchange rates. While these painful structural adjustments were designed to correct fiscal imbalances, the administration recognized the urgent necessity of cushioning the vulnerable population through targeted social interventions and economic stimulus packages.
By late 2023 and early 2024, the legal and operational frameworks for critical credit institutions were fast-tracked. NELFUND was operationalized to provide interest-free loans to students in tertiary institutions, significantly alleviating the financial burden on struggling parents. Concurrently, CREDICORP was structured to roll out consumer credit frameworks, allowing credit-worthy citizens to acquire assets and pay over extended periods. The operationalization of the NCGC provided the definitive institutional guarantee needed to de-risk SME lending, culminating in the impressive performance metrics recorded at the close of its first operational year in late 2024 and early 2025.
Official Statements and Reactions from Stakeholders
The successes recorded by these financing schemes have elicited positive reactions from various economic analysts, business leaders, and education sector administrators. Stakeholders have particularly lauded the tangible impact of NELFUND, with recent reports from education authorities indicating that student loan availability has successfully reduced tertiary institution dropout rates by notable margins, keeping thousands of young Nigerians in school who would have otherwise abandoned their studies due to financial destitution.
Business advocacy groups, including chambers of commerce and manufacturing associations, have equally commended the risk-sharing model of the NCGC. Industry leaders have frequently lamented that high interest rates and collateral requirements have historically crippled promising indigenous enterprises. By mitigating these risks, the federal government is perceived to be actively listening to the structural grievances of the private sector.
Reflecting on these milestones, President Tinubu emphasized that his administration’s primary objective has always been to translate structural macroeconomic reforms into practical, life-changing opportunities for ordinary citizens.
"When I sought your mandate, I promised to move Nigeria towards a credit-based economy and to establish a loan guarantee scheme that would help small businesses overcome the barriers that keep them from finance," President Tinubu stated. "That promise was about something practical. A worker with access to credit can buy what the family needs and pay over time, and a small business can invest today against the income it expects tomorrow."
The President further elaborated on the mechanics of the NCGC, addressing the perennial issue of collateral deficiencies that frustrate innovative entrepreneurs.
"Many viable businesses still meet the same obstacle at the bank. Lenders see too much risk in a sound business when the owner has little collateral or no credit history. We established NCGC to help change that. It carries part of the lending risk with participating financial institutions, giving them greater confidence to lend to businesses and borrowers they might otherwise turn away," he explained.
Future Outlook and Administration Commitments
Looking ahead, the federal government has signaled its firm commitment to scaling up these interventions. As the institutional frameworks mature, the administration intends to expand partnerships with additional commercial and microfinance banks, incorporating more financial institutions into the risk-sharing and consumer credit networks.
The overarching vision remains clear: to widen the financial highway until every Nigerian household and small enterprise, regardless of geographic location or socio-economic background, can access the capital required to build a prosperous future. By systematically dismantling the institutional barriers that have historically stifled domestic credit growth, the Tinubu administration is laying a resilient financial foundation designed to support sustainable, inclusive economic development for decades to come.