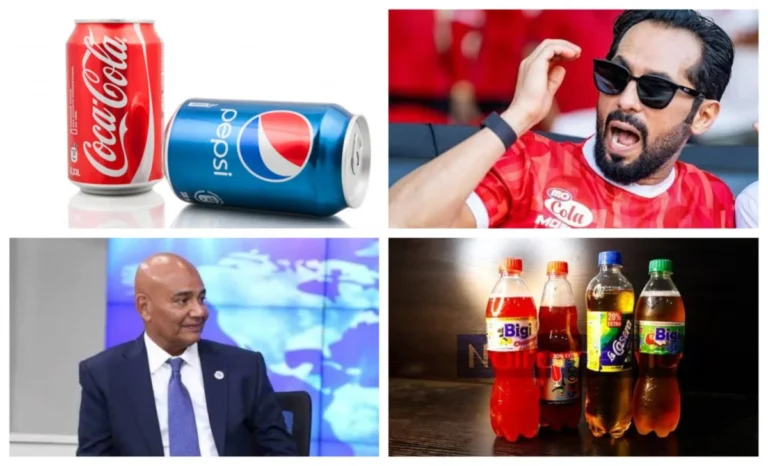
The global beverage landscape is undergoing a profound structural shift, characterized by fierce corporate trench warfare in North America and an unprecedented surge of localized competition across the African continent. While legacy titans Coca-Cola and PepsiCo continue their high-stakes tug-of-war for lucrative institutional contracts in the United States—ranging from fast-food chains to global hospitality conglomerates—a formidable wave of homegrown African manufacturers is rising to challenge their historic dominance. Backed by hundreds of millions of dollars in capital expenditure, local tycoons and indigenous brands are aggressively expanding factory footprints, optimizing distribution channels, and undercutting multinational pricing models. This dual-front pressure forces both Coca-Cola and PepsiCo to constantly defend their turf at home while fighting to secure their futures in one of the world’s fastest-growing consumer markets.
The Corporate Shakeup: Seismic Shifts in the American Beverage Market
The rivalry between Coca-Cola and PepsiCo reached a boiling point in the United States, marked by high-profile defections that reshaped the institutional dining and hospitality sectors. For decades, exclusive beverage contracts with major restaurant chains, entertainment venues, and hotel networks have served as stable pillars of revenue and brand visibility for the two cola giants. However, recent commercial realignments have demonstrated that even the most deeply entrenched partnerships are vulnerable to shifting corporate strategies and consumer preferences.
The most notable blow to PepsiCo arrived when Kentucky Fried Chicken (KFC) announced a monumental departure from its four-decade partnership. Effective at thousands of restaurants across the United States, KFC phased out Pepsi products to make way for Coca-Cola beverages. This massive transition mirrored similar victories for Coca-Cola, including wholesale retail giant Costco returning to Coca-Cola products within its high-traffic food courts and a comparable supplier swap executed at the iconic Indianapolis Motor Speedway.
Further cementing this momentum, Marriott International delivered another major setback to PepsiCo by terminating a 34-year global alliance. Marriott selected Coca-Cola as its exclusive worldwide beverage supplier across more of its global properties.
Despite these losses, PepsiCo has proven resilient, engineering vital counter-offensives to protect its market share. The company successfully snatched Subway’s United States beverage contract away from Coca-Cola and secured a crucial, long-term extension of its partnership with Taco Bell. These high-stakes maneuvers illustrate that the domestic war for corporate accounts remains fiercely contested, with neither giant able to claim permanent supremacy.
The African Frontier: Local Titans Challenge Multinational Hegemony
While Coca-Cola and PepsiCo trade blows in Western markets, an equally compelling and potentially more transformative economic battle is unfolding across Africa. For generations, multinational corporations enjoyed largely unchallenged dominance across the continent’s emerging economies. Today, however, a new generation of African industrialists, entrepreneurs, and regional manufacturing groups are challenging that status quo. By leveraging intimate knowledge of local consumer preferences, localized supply chains, and aggressive pricing strategies, these indigenous brands are capturing substantial market share.
The narrative of this localized uprising is anchored by heavyweight regional players who are pouring unprecedented capital into production infrastructure. Tanzanian billionaire Mohammed Dewji, head of the MeTL Group, laid out his expansionist vision during a high-profile interview, explicitly stating his intention to compete toe-to-toe with the American colossus. True to his word, Dewji’s enterprise has advanced aggressive regional expansion strategies, including a multi-million-dollar investment in a modern soft drinks manufacturing facility in Mombasa, Kenya. The strategic intent is clear: to produce high-quality, locally tailored beverages at a price point that undercuts imported or multinational-licensed alternatives.
Simultaneously, fellow Tanzanian industrialist Said Salim Bakhresa spearheaded a massive expansion of his group’s Azam beverage manufacturing complex. The capital injection supercharged the company’s production capacity, effectively doubling daily output to hundreds of thousands of cartons. With an extensive distribution network spanning East and Central Africa, the combined investments of Dewji and Bakhresa signal a formidable East African bloc determined to rewrite the rules of the regional beverage economy.
West and North Africa Join the Industrial Surge
The challenge to multinational dominance is not confined to East Africa; it is a pan-continental phenomenon. In Nigeria, Africa’s most populous nation and largest economy, indigenous manufacturer Rite Foods—owned and driven by the Adegunwa family—has invested heavily in expanding production capacity at its massive facility in Ogun State. These capital outlays have tripled the output of the company’s flagship Bigi soft drinks range, enabling it to mount a serious, sustained challenge against the established footprints of both Coca-Cola and PepsiCo in the West African giant.
Nigeria’s carbonated soft drink sector has seen further disruption from dynamic players like Mamuda Beverages, whose Pop Cola brand has experienced meteoric growth. Market intelligence firms have recognized the company as one of the most agile and rapidly expanding carbonated beverage producers in the region, proving that local consumers are increasingly receptive to homegrown alternatives.
Moving northward, Egypt’s V7 has rapidly scaled its manufacturing capabilities. Founded by entrepreneur Mohamed Nour and his partners, the brand inaugurated a state-of-the-art production facility, backed by tens of millions of dollars in initial investments, with even larger capital expenditures slated for the coming years to capture a dominant share of the North African market.
Similarly, the Mali-founded Gaselia Group has executed a multi-million-euro investment program, establishing a robust manufacturing presence across West Africa. By setting up advanced beverage plants in countries like Guinea, Mali, and Côte d’Ivoire, Gaselia has built an interconnected regional supply chain capable of competing directly with multinational distribution networks.
In East-Central Africa, Uganda’s Hariss International has continued its aggressive trajectory through the expansion of its Riham beverage portfolio, backed by substantial capital investments in manufacturing plants and logistics infrastructure.
Chronology of Market Shifts and Investments (2023–2026)
- 2023: Tanzanian billionaire Mohammed Dewji publicly declares his ambition to build a manufacturing footprint designed to challenge Coca-Cola and PepsiCo directly across Africa. Concurrently, Uganda’s Hariss International invests nearly $100 million to upgrade its Riham production and distribution facilities.
- 2025: Said Salim Bakhresa’s industrial group initiates a $500 million expansion of the Azam beverage factory in Mwandege to double daily carton production. Meanwhile, Nigeria’s Mamuda Beverages is named the country’s most dynamic carbonated drinks company by market researchers.
- May 2026: Mohammed Dewji’s MeTL Group announces a $50 million investment in a soft drinks factory in Mombasa, Kenya. Concurrently, Egypt’s V7 opens a new manufacturing plant as part of its multi-phase regional expansion plan.
- October 2026: Kentucky Fried Chicken (KFC) delivers a major blow to PepsiCo by announcing the transition from Pepsi to Coca-Cola products across 3,600 United States restaurants, ending a 40-year partnership. This follows Marriott International’s global switch to Coca-Cola earlier in the year, while PepsiCo counters by securing Subway’s U.S. contract and extending its Taco Bell agreement through 2036.
Market Implications and Economic Analysis
The simultaneous pressures facing Coca-Cola and PepsiCo—fighting defensive corporate battles in the West while confronting aggressive localized insurgents in Africa—highlight a broader evolution in the global fast-moving consumer goods (FMCG) sector. For decades, multinational corporations relied on scale, standardized global marketing, and entrenched distribution networks to maintain unassailable market positions. However, the rise of well-capitalized regional competitors demonstrates that modern consumers, particularly in emerging markets, increasingly gravitate toward brands that reflect local identity, offer superior value during inflationary periods, and are backed by responsive regional supply chains.
The structural implications of these developments are profound. As African billionaires and indigenous manufacturing syndicates pour hundreds of millions of dollars into automated factories, cold-chain logistics, and hyper-local distribution networks, they are creating resilient economic ecosystems that are less vulnerable to global currency fluctuations and international supply chain disruptions.
For Coca-Cola and PepsiCo, the playbook must adapt. Maintaining market leadership in Africa will increasingly require more than just exporting global formulas; it demands deep localization, competitive pricing, agile supply chain management, and strategic partnerships with regional players. As local brands continue to gain scale, replicate the successes of independent challengers in parts of Asia and Europe, and capture the loyalty of a youthful, fast-growing African demographic, the duopoly that has defined the global beverage industry for over a century faces its most dynamic and decentralized challenge yet.