The geopolitical landscape of modern warfare is undergoing a profound and rapid transformation, driven primarily by the unprecedented proliferation and tactical integration of military drones. According to comprehensive data analysis derived from the Stockholm International Peace Research Institute (SIPRI) and visualized by market analysts, the international trade of unmanned aerial systems (UAS) is heavily concentrated around two major regional theaters: the protracted war in Ukraine and volatile security crises spanning the African continent. While traditional defense heavyweights continue to dictate the upper echelons of military hardware exports, emerging powers such as China, Iran, and Türkiye have successfully cemented their status as critical defense suppliers, reshaping alliances and redefining tactical doctrines across multiple hemispheres.
The European Theater: A Megascale Crucible for Unmanned Systems
The ongoing war between Russia and Ukraine has completely revolutionized modern military technology, serving as the single largest catalyst for the global drone trade. Between 2022 and 2025, the demand generated by this singular conflict overshadowed all other global military acquisitions combined, highlighting the indispensable role that aerial reconnaissance, precision targeting, and kamikaze drone strikes now play in conventional state-on-state combat.
Data compiled from international monitoring agencies reveals that Ukraine alone imported 8,664 major military drones from foreign allies during this four-year window, capturing a staggering 51.5 percent of the global market share. The vast majority of Kyiv’s external military drone procurement—approximately 83 percent—was sourced directly from the United States, illustrating the deep defense cooperation between Washington and Kyiv. Beyond foreign imports, Ukraine has fostered a massive, decentralized domestic defense manufacturing sector. According to official figures released by Ukraine’s National Security and Defence Council, the nation’s domestic industrial capacity has scaled exponentially, enabling the production of over 8 million First-Person View (FPV) drones annually. These locally manufactured, inexpensive systems have become the backbone of tactical infantry support and frontline defense.
On the opposing side, the Russian Federation imported 6,720 major military drones during the same timeframe, accounting for 39.9 percent of the global total. Combined, Russia and Ukraine absorbed over 91 percent of all major military drone imports recorded worldwide between 2022 and 2025. In the early phases of the full-scale invasion, Moscow relied heavily on foreign acquisitions, notably purchasing substantial quantities of Iranian-designed Shahed-136 loitering munitions. These long-range delta-wing drones were deployed extensively to target Ukrainian critical infrastructure, power grids, and urban centers.
However, following initial reliance on external suppliers, Moscow rapidly invested in domestic industrial scaling. Collaborating with foreign partners to establish local manufacturing hubs, Russia began producing its own domestic variant known as the Geran-2. According to assessments from Ukraine’s Defence Intelligence directorate, Russian domestic production lines have achieved massive outputs, currently manufacturing roughly 2,800 Geran-2 drones per month. This industrial shift has reduced Moscow’s reliance on direct foreign imports while maintaining high-volume operational tempos on the battlefield.
Africa’s Rising Drone Dependence: Counterinsurgency in the Sahel and Central Africa
While European imports are defined by high-intensity, high-volume state warfare, the integration of military drones in Africa represents a strategic shift toward counterinsurgency, border security, and asymmetric warfare. Between 2022 and 2025, a select group of African nations imported 107 major military drones. Although this figure represents a minor fraction of the nearly 17,000 systems recorded globally, it underscores a critical tactical evolution in how African armed forces are confronting persistent jihadist insurgencies, separatist movements, and localized militia groups.
The Democratic Republic of Congo (DRC) emerged as Africa’s top importer of major military drones during the analyzed period, receiving 29 systems from foreign suppliers—a volume that places the nation 12th globally. Facing severe security instability in the eastern provinces, the Congolese government has deployed Chinese-made CH-4 Rainbow medium-altitude, long-endurance (MALE) drones. These platforms have been actively utilized in reconnaissance and strike operations against the M23 rebel movement and various other armed factions destabilizing the region.
Following the DRC, Sudan recorded 17 drone imports, while Mali secured 15 systems. Both nations have increasingly turned to foreign defense markets to bolster their counter-terrorism capabilities. Sudan and Mali have notably integrated Turkish-made military hardware into their armed forces, most notably the combat-proven Bayraktar TB2. Furthermore, Mali has taken significant steps to enhance its aerial strike capabilities by procuring and deploying the heavier Turkish Akıncı drone model. These advanced systems provide Malian forces with extended operational ranges, higher payload capacities, and sophisticated surveillance equipment required to combat heavily armed jihadist and separatist groups operating across the expansive Sahel region.
Other regional actors have similarly updated their defense portfolios to include unmanned capabilities. Burkina Faso and Morocco each imported 10 major military drones during the four-year window. Niger and Nigeria acquired seven systems apiece, while Algeria and Kenya recorded six imports each. Together, these nine nations highlight a broader continental trend: African militaries are increasingly looking away from traditional Western suppliers, pivoting instead toward diverse international partners that offer rapid delivery timelines with fewer political prerequisites.
Global Mid-Tier Demand and Diversification of Suppliers
Beyond the towering figures recorded in Eastern Europe and the targeted acquisitions seen in Africa, the wider global defense market reveals steady demand among mid-tier military powers seeking to modernize their armed forces with indigenous or imported drone technology.
Ranking third globally—far behind the Ukrainian and Russian totals but significantly ahead of other mid-tier nations—Taiwan imported 291 military drones between 2022 and 2025. This acquisition strategy aligns with Taipei’s ongoing asymmetric defense transformation plan, known as the overall defense concept, which emphasizes mobile, low-cost, and survivable weapon systems designed to deter potential amphibious aggression. South Korea followed closely in fourth place with 190 imported systems, reflecting Seoul’s continuous efforts to upgrade its aerial reconnaissance and border-monitoring capabilities in response to persistent tensions on the Korean Peninsula.
Azerbaijan, which famously utilized unmanned aerial systems to decisive effect during the 2020 Nagorno-Karabakh war, recorded 154 drone imports. India secured sixth place globally with 119 imports, running parallel to its ambitious domestic "Make in India" defense initiative aimed at transitioning the nation from a major arms importer into a self-reliant manufacturing hub for autonomous military technology. Other notable importers include Georgia with 100 systems, Albania with 56, and both Hungary and Lithuania with 50 units each, reflecting NATO’s eastern flank members rapidly updating their surveillance and defensive doctrines.
Geopolitical Shifts and the Rise of New Defense Powerhouses
The shifting dynamics of the international drone trade have effectively dismantled traditional Cold War-era monopoly models on advanced military hardware exports. For decades, the global arms market was predominantly anchored by the United States and a handful of European defense contractors. However, the high demand for cost-effective, proven unmanned systems has enabled nations like Türkiye and China to capture massive market share across the Global South.
Türkiye, through private defense firms like Baykar, has emerged as a premier global exporter of high-performance tactical drones. The Bayraktar TB2, in particular, has achieved legendary status in military circles due to its combat effectiveness in conflicts ranging from Nagorno-Karasabakh and Ukraine to Libya and the Sahel. By offering versatile platforms without the stringent bureaucratic and diplomatic export hurdles often imposed by Western governments, Ankara has successfully deepened its diplomatic and economic footprint across Africa and the Middle East.
Similarly, Beijing has cemented its position as a primary supplier of affordable, capable combat drones to developing nations. Through state-backed defense conglomerates, China provides nations such as the DRC, Nigeria, and various Middle Eastern states with medium- and high-altitude drones, filling a critical capability gap for governments that lack access to restricted Western technology.
Meanwhile, Iran’s emergence as a major defense exporter—demonstrated by its supply of loitering munitions to Russia and regional proxies—highlights how sanctioned nations can leverage asymmetric technological capabilities to project geopolitical influence. Conversely, the United States remains the preeminent supplier of high-end, sophisticated reconnaissance and strike platforms, though its export policies remain strictly regulated through the International Traffic in Arms Regulations (ITAR) and the Missile Technology Control Regime (MTCR).
Methodological Limitations: Understanding the Broader Market
Despite providing invaluable insights into state-level military acquisitions, international databases such as those maintained by SIPRI capture only a portion of the true global drone economy. The reported figures primarily account for major military-grade systems—such as MALE drones, loitering munitions, and large tactical platforms—while largely omitting smaller FPV drones, quadcopters, and commercial off-the-shelf (COTS) devices.
Furthermore, these trade statistics frequently encompass systems supplied as direct military aid, grants, or platforms produced within recipient nations under foreign manufacturing licenses. Because thousands of small-scale commercial drones are routinely modified for combat use with improvised explosive devices (IEDs) in modern conflicts, the true number of operational drones utilized in zones like Ukraine, Sudan, and the Sahel is exponentially higher than official import metrics suggest.
Strategic Implications for Future Conflict
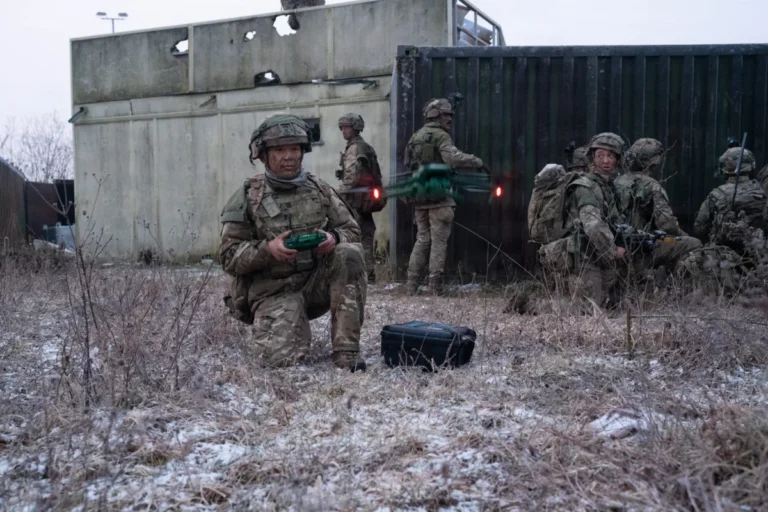
The transformation of the global military drone trade carries profound implications for future geopolitical stability. As unmanned systems democratize precision strike capabilities—allowing even cash-strapped insurgent groups and minor state militaries to project lethal force at a fraction of the cost of traditional manned aircraft—defense doctrines worldwide are being rewritten.
Traditional concepts of air superiority are being challenged by swarming tactics, low-cost loitering munitions, and electronic warfare countermeasures. As long as high-intensity conflicts persist in Europe and complex insurgencies challenge state authority in Africa, global demand for unmanned aerial systems will remain at historic highs. Consequently, the international arms market will continue to diversify away from traditional Western monopolies, empowering new defense manufacturing nations and permanently altering the balance of military power across the globe.