The backbone of Nigeria’s economy, consisting of millions of Micro, Small, and Medium-sized Enterprises (MSMEs), is currently teetering on the edge of a structural collapse. According to the 2025 Informal Economy Report released by Moniepoint, a leading fintech player, the vast majority of these enterprises are trapped in a perpetual cycle of subsistence, unable to transition from survival-mode operations to scalable, growth-oriented businesses. The report, which synthesized data from over 5 million businesses and extensive field surveys, paints a grim picture of an ecosystem where revenue growth is being systematically cannibalized by soaring operational costs, inflationary pressures, and a volatile currency.
The Profitability Paradox: Growth Without Gains
The most alarming takeaway from the report is the disconnect between revenue and net profit. While 65% of the businesses surveyed reported an increase in total revenue over the past year, only 47% recorded a corresponding rise in profit. This "profit squeeze" is the defining narrative of the Nigerian informal sector in 2025.
The data indicates that 38% of SMEs earn less than 10,000 naira ($6.78) in profit daily, while 70% of the entire sector generates less than 50,000 naira ($33.89) in daily profit. Even more stark is the median profit range, which sits at a razor-thin 10,000 to 20,000 naira. When these figures are adjusted for the current cost of living in Nigeria, it becomes clear that most of these businesses are not creating wealth; they are merely managing cash flow to cover the most basic daily overheads.
A Chronology of Economic Instability
To understand the current malaise, one must look at the timeline of events that have reshaped the Nigerian economic landscape since mid-2023. The primary catalyst was the government’s shift toward a unified foreign exchange policy, which, while intended to improve long-term transparency, resulted in an immediate and violent devaluation of the naira.
- June 2023: The Central Bank of Nigeria (CBN) moved to float the naira, allowing market forces to dictate the exchange rate. The currency plummeted from roughly 460 NGN/USD to nearly 1,600 NGN/USD over the following two years.
- Late 2023: As the naira lost approximately 70% of its value, import-dependent businesses faced an immediate crisis. The cost of raw materials, energy, and logistics spiked, as the majority of goods circulating in the informal market were linked to imported inputs.
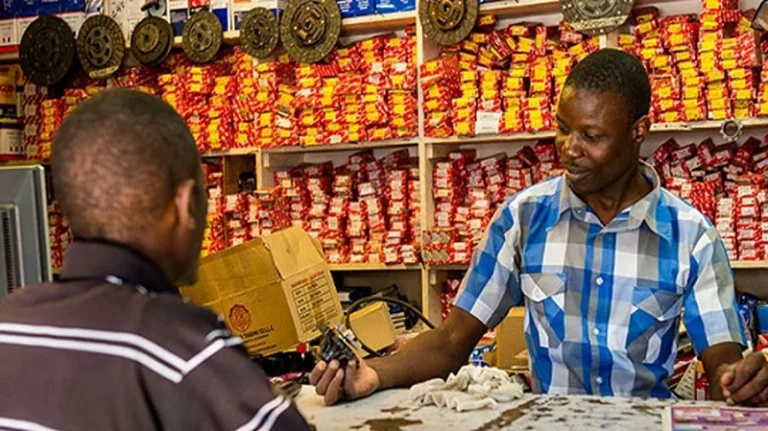
- Throughout 2024: Inflationary pressures reached a 28-year high. Transport costs, driven by the removal of fuel subsidies and the rising cost of imported automotive parts, created a bottleneck in supply chains that disproportionately affected small-scale traders and producers.
- Early 2025: The current data confirms that the cumulative effect of these policies has decimated the profit margins of MSMEs, which historically contribute 65% of Nigeria’s GDP and account for over 80% of total employment.
The Gender Gap in Economic Resilience
The report also highlights a troubling disparity in how different demographics are weathering the storm. Women-owned SMEs, which represent a significant portion of the informal economy, are disproportionately affected by the current downturn.
Data shows that 41% of women entrepreneurs earn less than 10,000 naira in daily profit, compared to 34% of their male counterparts. Furthermore, the upper echelon of the informal sector—those earning above 50,000 naira daily—is dominated by men at a rate of 16%, compared to just 10% for women. These figures suggest that structural barriers, including unequal access to capital, digital literacy tools, and traditional networking, are exacerbating the economic divide for female entrepreneurs in Nigeria.
The Cost of Doing Business: A Quantitative Breakdown
The "Survival Check" analysis within the Moniepoint report provides a chilling look at the lack of a safety net for most business owners. Approximately 42% of Nigerian businesses operate with a savings buffer that would last them one month or less if their income were to cease today.
This lack of liquidity is compounded by the fact that 79% of respondents reported a "significant or slight increase" in their cost of doing business over the last 12 months. When asked about their savings habits, the data revealed a concerning downward trend: only 74% of businesses are currently able to save money, a sharp decline from the 92.4% recorded in the previous reporting period.
The decline in savings is a leading indicator of future business failures. As the report notes, because informal businesses have developed a deep-seated aversion to formal bank loans—due to high interest rates and rigorous, often exclusionary, collateral requirements—their own savings are their only lifeline for expansion or emergency response. When those savings vanish, the business usually folds.
Official Perspectives and Policy Implications
Nurudeen Abubakar Zauro, Technical Advisor to the President on Economic and Financial Inclusion, acknowledges the severity of the situation. "The value of the Naira against foreign currencies depreciated significantly, which forced price hikes on imported commodities and reduced consumer purchasing power," Zauro stated. He noted that these bottlenecks have not only caused bankruptcy among SMEs but have effectively diminished the overall contribution of the informal economy to the national GDP.
The consensus among economic analysts is that the current, fragmented approach to SME support is insufficient. Foyinsolami Akinjayeju, CEO of Enhancing Financial Inclusion & Advancement, argues that there is an urgent need for a "coordinated, systemic" policy shift. Rather than offering one-off grants or loans, the government must look at the structural transformation of these enterprises.
Chinyere Almona, Director-General of the Lagos Chamber of Commerce and Industry (LCCI), emphasizes the need for capacity building. "If informal businesses are to evolve into growth-oriented employers, policies must deliberately target their transition from survivalist enterprises to scalable ventures," Almona said. She suggests that local chambers of commerce and trade associations should serve as hubs for upskilling, focusing on core competencies like bookkeeping, digital inventory management, and technical training.
Implications for the Future of the Informal Sector
The findings present a stark choice for policymakers. If the informal economy continues to act as a "shock absorber" for the national economy without receiving targeted, structural support, the risk of a widespread collapse of the MSME sector becomes a reality.
The primary barrier is the inability of these businesses to convert revenue into profit. As long as supply chain logistics remain expensive, energy costs stay high, and access to affordable credit remains out of reach, these businesses will continue to struggle. The "survival mode" is not a temporary state; it is becoming a permanent condition for the majority of Nigerian entrepreneurs.
For the Nigerian government, the path forward requires more than just macroeconomic stability. It requires the deliberate integration of the informal sector into the formal financial system through simplified tax structures, digital infrastructure that lowers the cost of transaction, and, crucially, a policy framework that prioritizes the growth of the local manufacturing and supply base to reduce the reliance on expensive, foreign-denominated imports. Without such measures, the engine of Nigeria’s economy risks stalling entirely, leaving millions of citizens without the means to participate in the formal workforce or drive the country’s long-term economic development.