Nigeria’s macroeconomic landscape has shifted significantly following the release of the latest consumer price index figures by the National Bureau of Statistics (NBS). Headline inflation slowed considerably to 14.06% in October 2026, dropping from 14.63% in September. This notable deceleration brings the inflation rate to its lowest level in more than six years, a milestone not witnessed since September 2020 when inflation printed at 13.71% before climbing to 14.23% the following month.
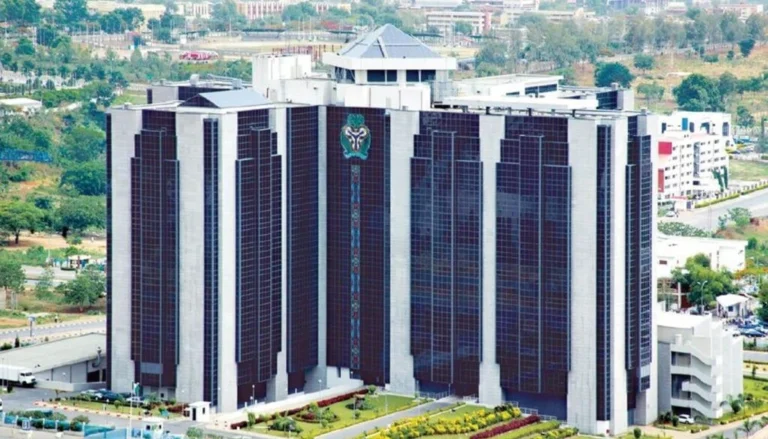
This unexpected and broad-based moderation has fundamentally altered the discourse surrounding the Central Bank of Nigeria (CBN) Monetary Policy Committee (MPC) meeting scheduled for November 23–24, 2026. Prior to the release of the October data, market consensus strongly favored a policy hold at the current Monetary Policy Rate (MPR) of 23%. However, the latest figures—characterized by a contraction in both core and food price components on a month-on-month basis—have injected fresh momentum into arguments favoring a possible interest rate cut, or at the very least, forced a rigorous reassessment of monetary easing parameters among financial analysts and policymakers alike.
A Broader Disinflationary Trend Across Key Sectors
A deeper examination of the October 2026 consumer price data reveals a distinct departure from the trends observed in previous months. While the September inflation report offered encouragement primarily through a declining headline figure, underlying pressures remained stubborn. In September, food inflation lingered at 19.59%, and month-on-month core inflation accelerated sharply to 1.11% from a negative reading of -0.06% in August. These subterranean figures stoked skepticism regarding the durability of the disinflationary trajectory.
October, conversely, presented a more synchronized cooling across multiple economic indices. Annual headline food inflation eased to 19.13%, down from 19.59% in September. More impressively, core inflation—which strips away volatile agricultural produce and energy prices—contracted sharply to 10.78% from 12.95%.
On a month-on-month basis, the sub-indices tell an even more compelling story of price adjustment: food prices fell by 0.75%, while core inflation contracted by 0.53%, cleanly reversing the upward momentum of the previous month. The Food Price Index retreated from 152.28 points in September to 151.13 points in October, aided by softening prices for both domestic farm produce and imported food items.
Despite these broad-based annual improvements, underlying price rigidities remain visible within specific sectors. Overall month-on-month headline inflation ticked upward slightly to 0.43%, compared to 0.06% in September, indicating that average price levels continued to drift upward on a sequential basis. Furthermore, select non-food categories registered pronounced monthly increases: housing, water, electricity, gas, and other fuels rose by 1.97%; transport costs advanced by 1.86%; and restaurants and accommodation services recorded a 1.54% increase. These pockets of rising costs underscore the reality that while disinflation is taking root, systemic price pressures have not been entirely eradicated.
Monetary Policy Context and the 23% MPR Benchmark
The central question facing the CBN Monetary Policy Committee is whether the current macroeconomic environment provides sufficient policy space to reduce the Monetary Policy Rate from its elevated perch of 23%. With headline inflation settling at 14.06%, the real interest rate—measured simply as the gap between the MPR and headline inflation—stands at a wide positive margin of approximately nine percentage points.
This substantial buffer has historically provided the central bank with considerable latitude to adjust borrowing costs without immediately compromising its core mandate of price stability. However, the CBN’s historical posture, particularly its communication following prior rate adjustments, points toward a cautious and deliberate approach. When the apex bank implemented a major policy adjustment in September, it explicitly clarified that the recalibration did not signal the inauguration of an aggressive, uninhibited rate-cutting cycle.
Consequently, the MPC must weigh whether a single month of favorable inflation data provides adequate empirical justification to pivot further toward monetary easing, or if prudence demands maintaining the current stance until the trajectory proves resilient over a prolonged period.
Expert Perspectives: Analysts Split Between a Hold and a Marginal Cut
The release of the October inflation report has divided financial analysts and fixed-income strategists, transforming what was once a near-unanimous expectation for a policy hold into a nuanced debate pitting a status quo stance against the possibility of a modest rate reduction.
Igho Erakpotobo, Lead for Corporate Finance and Research at Futureview Financial Services Limited, maintains that the CBN will likely vote to keep the MPR anchored at 23%. Erakpotobo cautions against interpreting previous monetary adjustments as the definitive start of an easing cycle. He points to several external and domestic risk factors on the horizon, including seasonal foreign exchange demand heading into the festive period, anticipated spikes in liquidity driven by approaching election spending cycles, and the potential for tighter monetary conditions in the United States. While he concedes that a marginal 50-basis-point reduction remains theoretically possible, he views a substantial easing move as highly unlikely.
Offering a parallel perspective, Vincent Oshoma, Business Development Manager at Blue Marina Securities, notes that the six-year low in inflation undeniably strengthens the theoretical framework for monetary easing. Nevertheless, Oshoma expects the MPC to proceed with extreme caution. He emphasizes that the central bank faces the delicate task of balancing the growth-oriented benefits of lower domestic borrowing costs against the imperative of foreign exchange market stability, anchored inflation expectations, and the necessity of evaluating the lagged transmission effects of previous policy cuts. For Oshoma, sustainable and consistent declines in inflation over subsequent reporting periods will be prerequisite for any further easing.
Francis Nkem, Investment Analyst at Iron Capital Asset Management Limited, shares a similarly conservative outlook. Nkem projects either an outright policy hold or, at most, an incremental, marginal rate reduction. He highlights persistent food inflation risks, recent downward pressures on the local currency (the naira), political spending associated with forthcoming elections, and external monetary policy headwinds as critical variables that should discourage the MPC from embarking on aggressive monetary loosening.
Chronology of Nigeria’s Inflation Dynamics (2020–2026)
To contextualize the significance of the October 2026 inflation print, it is helpful to review the trajectory of Nigeria’s Consumer Price Index over recent years:
- September 2020: Headline inflation stood at 13.71%, marking the last time prior to late 2026 that the nation registered an inflation rate lower than the current 14.06% threshold.
- October 2020 – Late 2023: Inflation resumed a steady upward climb, exacerbated by structural supply chain bottlenecks, exchange rate harmonization policies, and the complete phasing out of fuel subsidies.
- 2024–2025: Headline inflation surged to multi-year highs, prompting the CBN’s Monetary Policy Committee to implement aggressive tightening measures, driving the MPR up to 23% and beyond to combat runaway price acceleration.
- Mid-2026: Monetary tightening began to yield visible disinflationary dividends, with month-on-month readings beginning to stabilize and annual figures turning downward.
- September 2026: Headline inflation moderated to 14.63%, though mixed signals in core and food components initially provoked market skepticism regarding underlying price trends.
- October 2026: Headline inflation dropped further to 14.06%, supported by simultaneous contractions in food and core inflation on a month-on-month basis, setting the stage for the pivotal November MPC meeting.
Implications for the Broader Economy and Financial Markets
The implications of the October 2026 inflation print extend far beyond central banking boardrooms, directly touching consumer purchasing power, corporate funding costs, and fixed-income portfolios.
For Nigerian households, the moderation in food inflation—though coming off extremely high historical bases—offers a modest reprieve from the acute cost-of-living crises that characterized the mid-2020s. However, because sequential month-on-month inflation ticked upward to 0.43% and essential non-food services such as housing and transport continued to rise, everyday consumers may not immediately perceive a dramatic improvement in their overall cost burdens.
For the corporate sector, a sustained deceleration in core inflation reduces input cost volatility, enabling businesses to plan capital expenditures and inventory management with greater precision. If the MPC ultimately decides to cut interest rates—even marginally—commercial borrowing costs could ease, providing a welcome stimulus to manufacturing, agricultural processing, and small and medium-sized enterprises (SMEs) struggling with high debt service obligations.
Conversely, fixed-income investors and institutional portfolio managers are closely monitoring the interest rate trajectory to optimize their asset allocations. A reduction in the MPR would likely trigger a downward repricing of Treasury bills and government bonds, altering yield curves and forcing investors to re-evaluate their exposure to sovereign debt instruments relative to riskier equities.
Conclusion: The MPC’s Defining Decision
As the Monetary Policy Committee convenes on November 23–24, 2026, it faces a defining moment in calibrating Nigeria’s economic course. The economic data presented in the October NBS report provides a compelling dual narrative.
On one hand, the arguments for monetary easing are robust: headline inflation has reached a six-year low of 14.06%, food price pressures are softening, core inflation has compressed sharply, and real interest rates remain comfortably positive. On the other hand, valid arguments for institutional patience persist: headline month-on-month inflation accelerated slightly, non-food services continue to trend upward, structural risks surrounding upcoming electoral spending remain acute, and the full transmission mechanism of previous rate adjustments has yet to fully manifest.
Ultimately, the debate before the central bank has evolved from a simple question of maintaining a static hold to a nuanced deliberation between extending the pause or executing a measured, cautious rate reduction. The decision reached by the committee will set the monetary tone for the conclusion of 2026 and offer vital signaling regarding Nigeria’s macroeconomic resilience entering the new year.