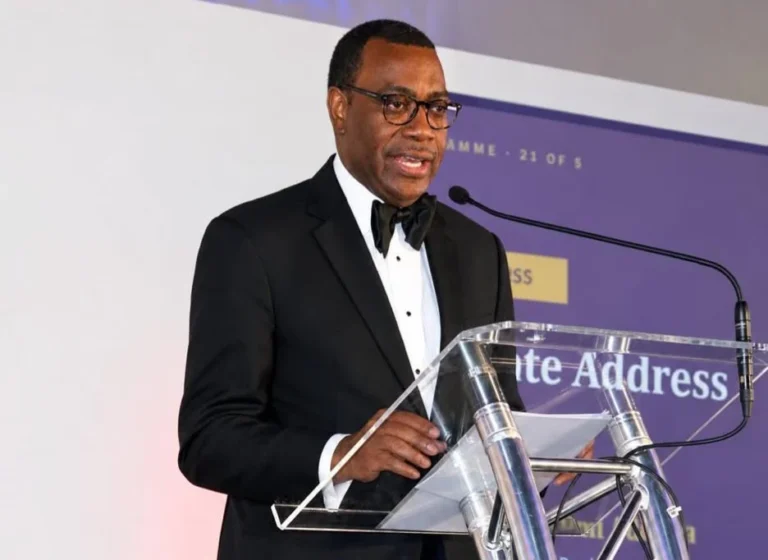
Former President of the African Development Bank Group, Dr. Akinwumi Adesina, has issued a stern challenge to the Nigerian insurance industry, calling for an era of radical transparency and enhanced corporate governance to reverse decades of public skepticism. Addressing industry leaders at the Nigeria Insurance Directors Conference in Lagos—an event co-hosted by the Chartered Insurance Institute of Nigeria and the National Insurance Commission—Adesina argued that the sector’s persistent inability to gain widespread consumer trust is fundamentally linked to a lack of accountability regarding claims settlement.
The conference, which served as a critical platform for discussing the future of the Nigerian insurance landscape, brought together regulators, board members, and industry experts to deliberate on the implementation of the Nigerian Insurance Industry Reform Act 2025. Dr. Adesina’s keynote address underscored a growing consensus among economic observers that the insurance sector remains a dormant giant in the nation’s financial system, largely due to systemic failures in service delivery.
The Transparency Imperative
At the heart of Adesina’s proposal is a call for the National Insurance Commission (NAICOM) to mandate the publication of an annual “Insurance Accountability and Performance Report.” This proposed document would move beyond basic financial disclosures and require insurers to provide granular data on claims received versus claims settled, the average time taken for disbursements, customer complaint logs, and detailed governance structures.
Adesina posited that the industry cannot effectively demand public confidence while maintaining a culture of opacity. “When a policyholder pays an insurance premium, that policyholder deserves a premium service in return,” he asserted, emphasizing that the true test of an insurance contract is not the ease of premium collection, but the efficiency and empathy displayed during the claims process.
Chronology of Sector Challenges
To understand the gravity of Adesina’s intervention, one must look at the historical context of the Nigerian insurance market. For decades, the industry has struggled with a reputation for bureaucratic delays, complex fine-print exclusions, and outright claims denial.
- 1990s–2000s: The sector suffered from fragmented regulations and numerous instances of insolvency, leading to the first major wave of consolidation.
- 2005–2007: The first major recapitalization exercise occurred, significantly increasing minimum capital requirements to weed out weaker players, though public trust failed to see a proportional uptick.
- 2010s: The emergence of digital banking and mobile money began to outpace the insurance sector, highlighting the lack of product innovation and consumer-centric technology in insurance.
- 2025: The introduction of the Nigerian Insurance Industry Reform Act marks the current turning point, aiming to modernize oversight and force institutions to align with global best practices.
Despite these legislative efforts, penetration remains stagnant at approximately 0.5% of the Gross Domestic Product (GDP). This figure stands in stark contrast to global averages, where insurance penetration in developed economies often exceeds 6% to 8% of GDP.
Data-Driven Reality: The Penetration Gap
The data indicates that Nigeria’s insurance sector is punching significantly below its weight. While the country possesses a massive, youthful population and a growing middle class, the disconnect between potential and reality is stark. According to industry statistics, the majority of the population views insurance as an unnecessary expense rather than a vital financial safeguard.
This low penetration is not merely a marketing problem; it is a structural failure. Without a robust insurance sector, the Nigerian economy is exposed to heightened risks. For instance, in the agricultural sector—which is central to the nation’s food security—the lack of comprehensive crop and weather-index insurance leaves millions of smallholder farmers vulnerable to climate shocks. Similar gaps exist in the manufacturing and infrastructure sectors, where the absence of adequate risk-transfer mechanisms complicates project financing and foreign direct investment.
Institutional Transformation vs. Recapitalization
A major point of contention in Adesina’s speech was the common misconception that increasing capital reserves equates to institutional strength. With the ongoing recapitalization exercise under the 2025 Reform Act, many firms are focused solely on meeting regulatory capital thresholds.

Adesina warned against this singular focus. “Recapitalization is not the same as institutional transformation,” he stated. He argued that capital is merely a buffer; true stability is derived from disciplined underwriting, the maintenance of adequate technical reserves, and sophisticated risk management frameworks. By prioritizing capital over conduct, he suggested that the industry risks creating “zombie” institutions that are well-funded but operationally stagnant.
The Role of Boards in Governance
Adesina placed the burden of reform squarely on the shoulders of the directors. He urged boards to move beyond a passive oversight role and take direct responsibility for claims performance. Under his proposed framework, board members would be held accountable for the “customer experience” as a key performance indicator, shifting the boardroom culture from one of compliance-based box-ticking to one of service-based value creation.
The call for better corporate governance comes at a time when the Nigerian financial services sector is under intense scrutiny. Strengthening board oversight is expected to curb the prevalence of insider-related lending and poor investment decisions, which have historically plagued some insurance firms during periods of economic volatility.
Broader Economic Implications
The potential for a revitalized insurance sector to drive Nigeria’s economic growth is immense. If the industry can achieve even a modest increase in penetration, it would unlock billions of naira in long-term investable capital. This capital is essential for funding long-term national projects, such as transport infrastructure, energy distribution, and healthcare systems.
By providing a safety net for productive assets, the insurance industry could act as a catalyst for credit expansion. When banks are confident that the assets they finance are backed by credible, well-capitalized insurance policies, they are more likely to lend to businesses, thereby fueling economic expansion.
Official Responses and Industry Outlook
While the National Insurance Commission has yet to issue a formal directive mirroring all of Dr. Adesina’s specific proposals, the mood at the conference suggested a receptive audience among younger, more tech-forward insurance executives. Several industry leaders have noted that the "reputation crisis" is the single biggest barrier to entry for the younger, digital-native generation of Nigerians.
Industry analysts suggest that if the industry adopts these transparency measures, it could trigger a "virtuous cycle." Increased transparency would lead to better claims ratios, which in turn would improve the industry’s brand equity, leading to higher premium volumes and, eventually, higher GDP penetration.
The Road Ahead: Success as an Outcome
Adesina’s concluding remarks served as a stern warning against the “culture of announcements” that has characterized the Nigerian financial sector for years. He emphasized that the measure of success must be outcomes—the number of families shielded from financial ruin, the number of businesses revived after disasters, and the tangible growth of the insurance sector’s contribution to national stability.
As the Nigerian insurance industry navigates the implementation of the 2025 reforms, the path forward appears clear: the sector must pivot from being a collector of premiums to a protector of value. Whether the industry will heed this call for transparency or continue to operate behind a veil of traditional opacity remains the defining question for the next decade of Nigerian finance. The pressure for change is no longer just coming from regulators; it is coming from the very top of the global economic leadership, signaling that the time for incremental change has passed, and the era of institutional transformation must begin.